Annual base rent before other occupancy costs.
Executive operating brief · October 2026
Turn eleven years of demand into predictable cash flow.
The food can carry a premium. The next operating system must defend that value, produce dependable cash and let Joe move from daily operator to owner, CEO and capital allocator.
Public evidenceManagement inputsOperating gates
THE MANDATE
Stabilize.
Monetize.
Then capitalize. AXLETE × JERSEY JO’S
Monetize.
Then capitalize. AXLETE × JERSEY JO’S
Operating history11 years
Monthly lease$7,000
Reported monthly sales$2K–$40K
North star$5M+ enterprise
PREMIUM EXPERIENCE MENU CLARITY DIGITAL CONVERSION PRODUCT IMAGERY RESTAURANT CONTRIBUTION CATERING PIPELINE MOBILE UTILIZATION WINTER RESERVE
01 / The executive read
A strong product.
A volatile operating system.
The public evidence suggests Jersey Jo’s has already solved the hardest restaurant problem: customers value the product. The next constraint is converting seasonal demand and owned assets into dependable contribution.
OPERATING THESIS
Cash flow first. Management depth second. Expansion third. Capital follows a business that works without Joe as the daily operating system.
Peak events can create cash. The next step is turning that cash into reserves, repeatable demand and the management capacity to carry winter.
DoorDash rating from 100+ ratings when reviewed.
Vehicles on 2nd Street SW per day.
Mayo employees in the city’s 2024 employer schedule.
Beds at Mayo Clinic Saint Marys Campus.
01IMMEDIATE
Construction is suppressing convenience now.
16th Avenue access from 2nd Street is currently constrained. High corridor traffic is not the same as easy restaurant access.
AXLETE ACTIONAccess messaging, pickup clarity, local search updates and source-coded offers.
02OBSERVED
Higher-value channels are undersold online.
The catering page is primarily image-based, while the food-truck page does not clearly expose a strong schedule and booking workflow.
AXLETE ACTIONPackages, minimums, lead form, response ownership and event calendar.
03DATA GATE
Channel economics are not yet separated.
A successful festival can hide a weak restaurant month—or restaurant cash can subsidize an unprofitable mobile event.
AXLETE ACTIONContribution P&Ls for restaurant, delivery, truck, trailer and catering.
04CAPITAL GATE
Property must follow normalized cash flow.
Ownership can build equity, but it replaces rent with debt service, tax, insurance, maintenance, reserves and execution risk.
AXLETE ACTIONLease, equipped-building and production-facility comparison.
02 / Public evidence
The market is visible.
The economics are not.
These public snapshots show product strength, mobile capacity and current access friction. POS, bank, payroll and event records will show which demand actually becomes retained cash.
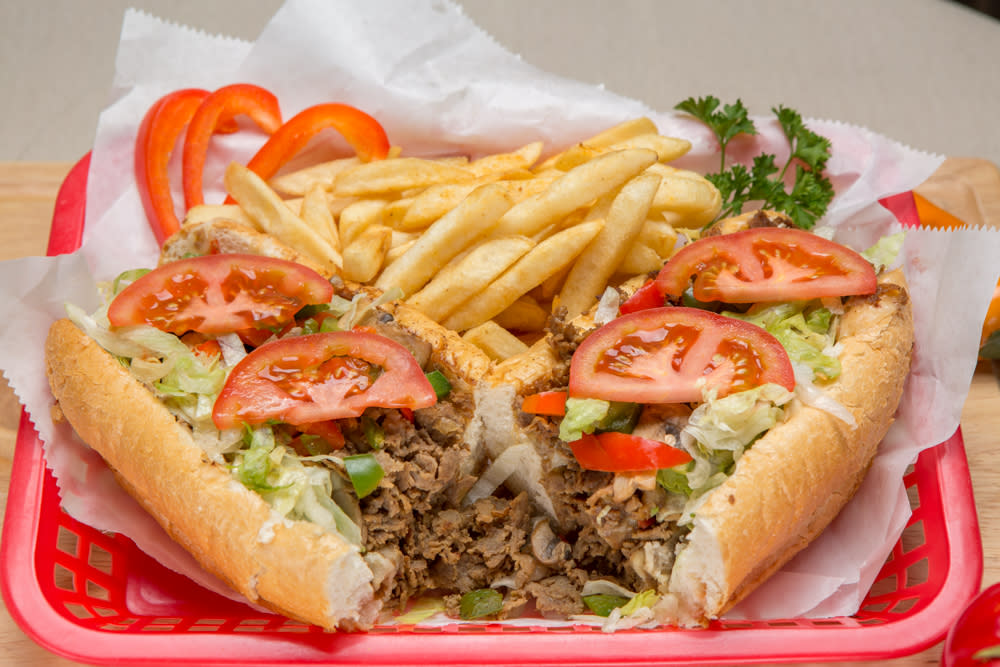
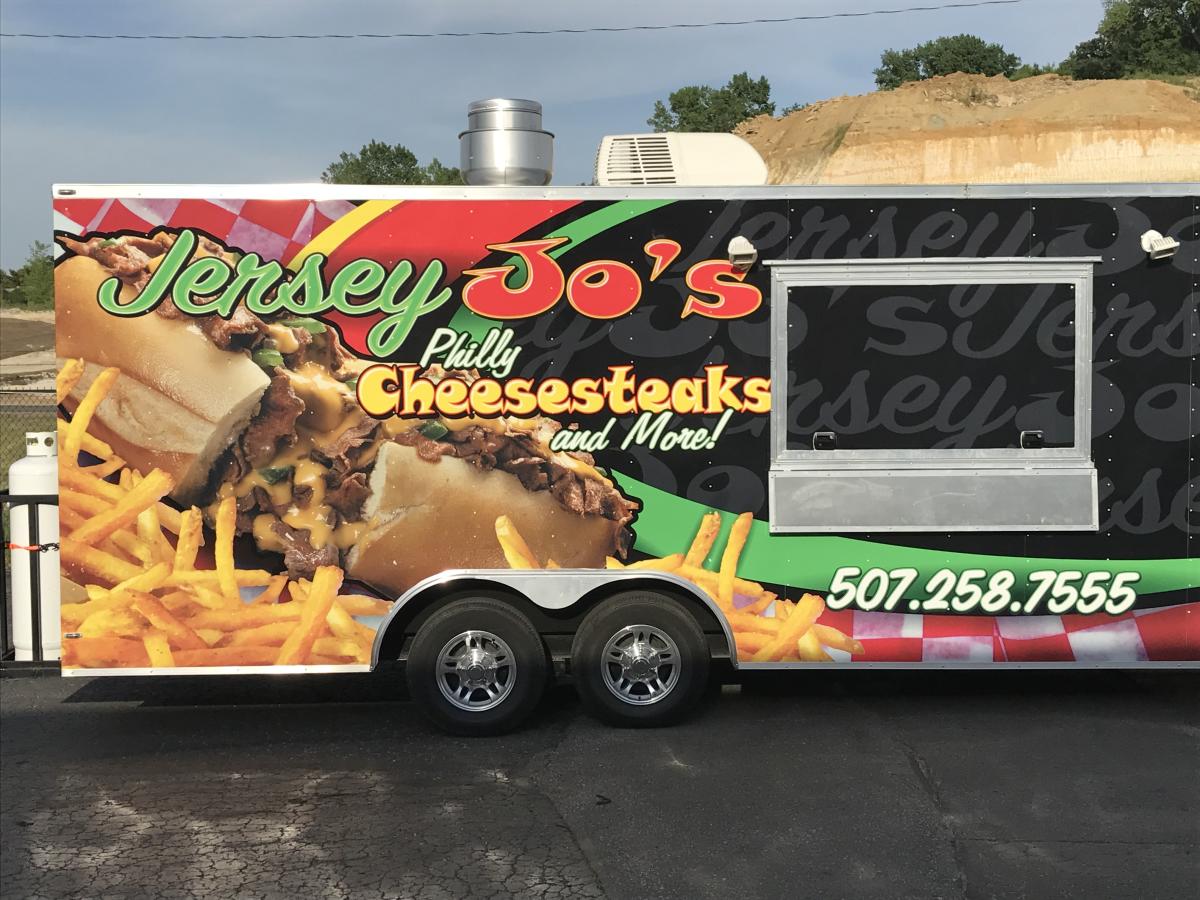
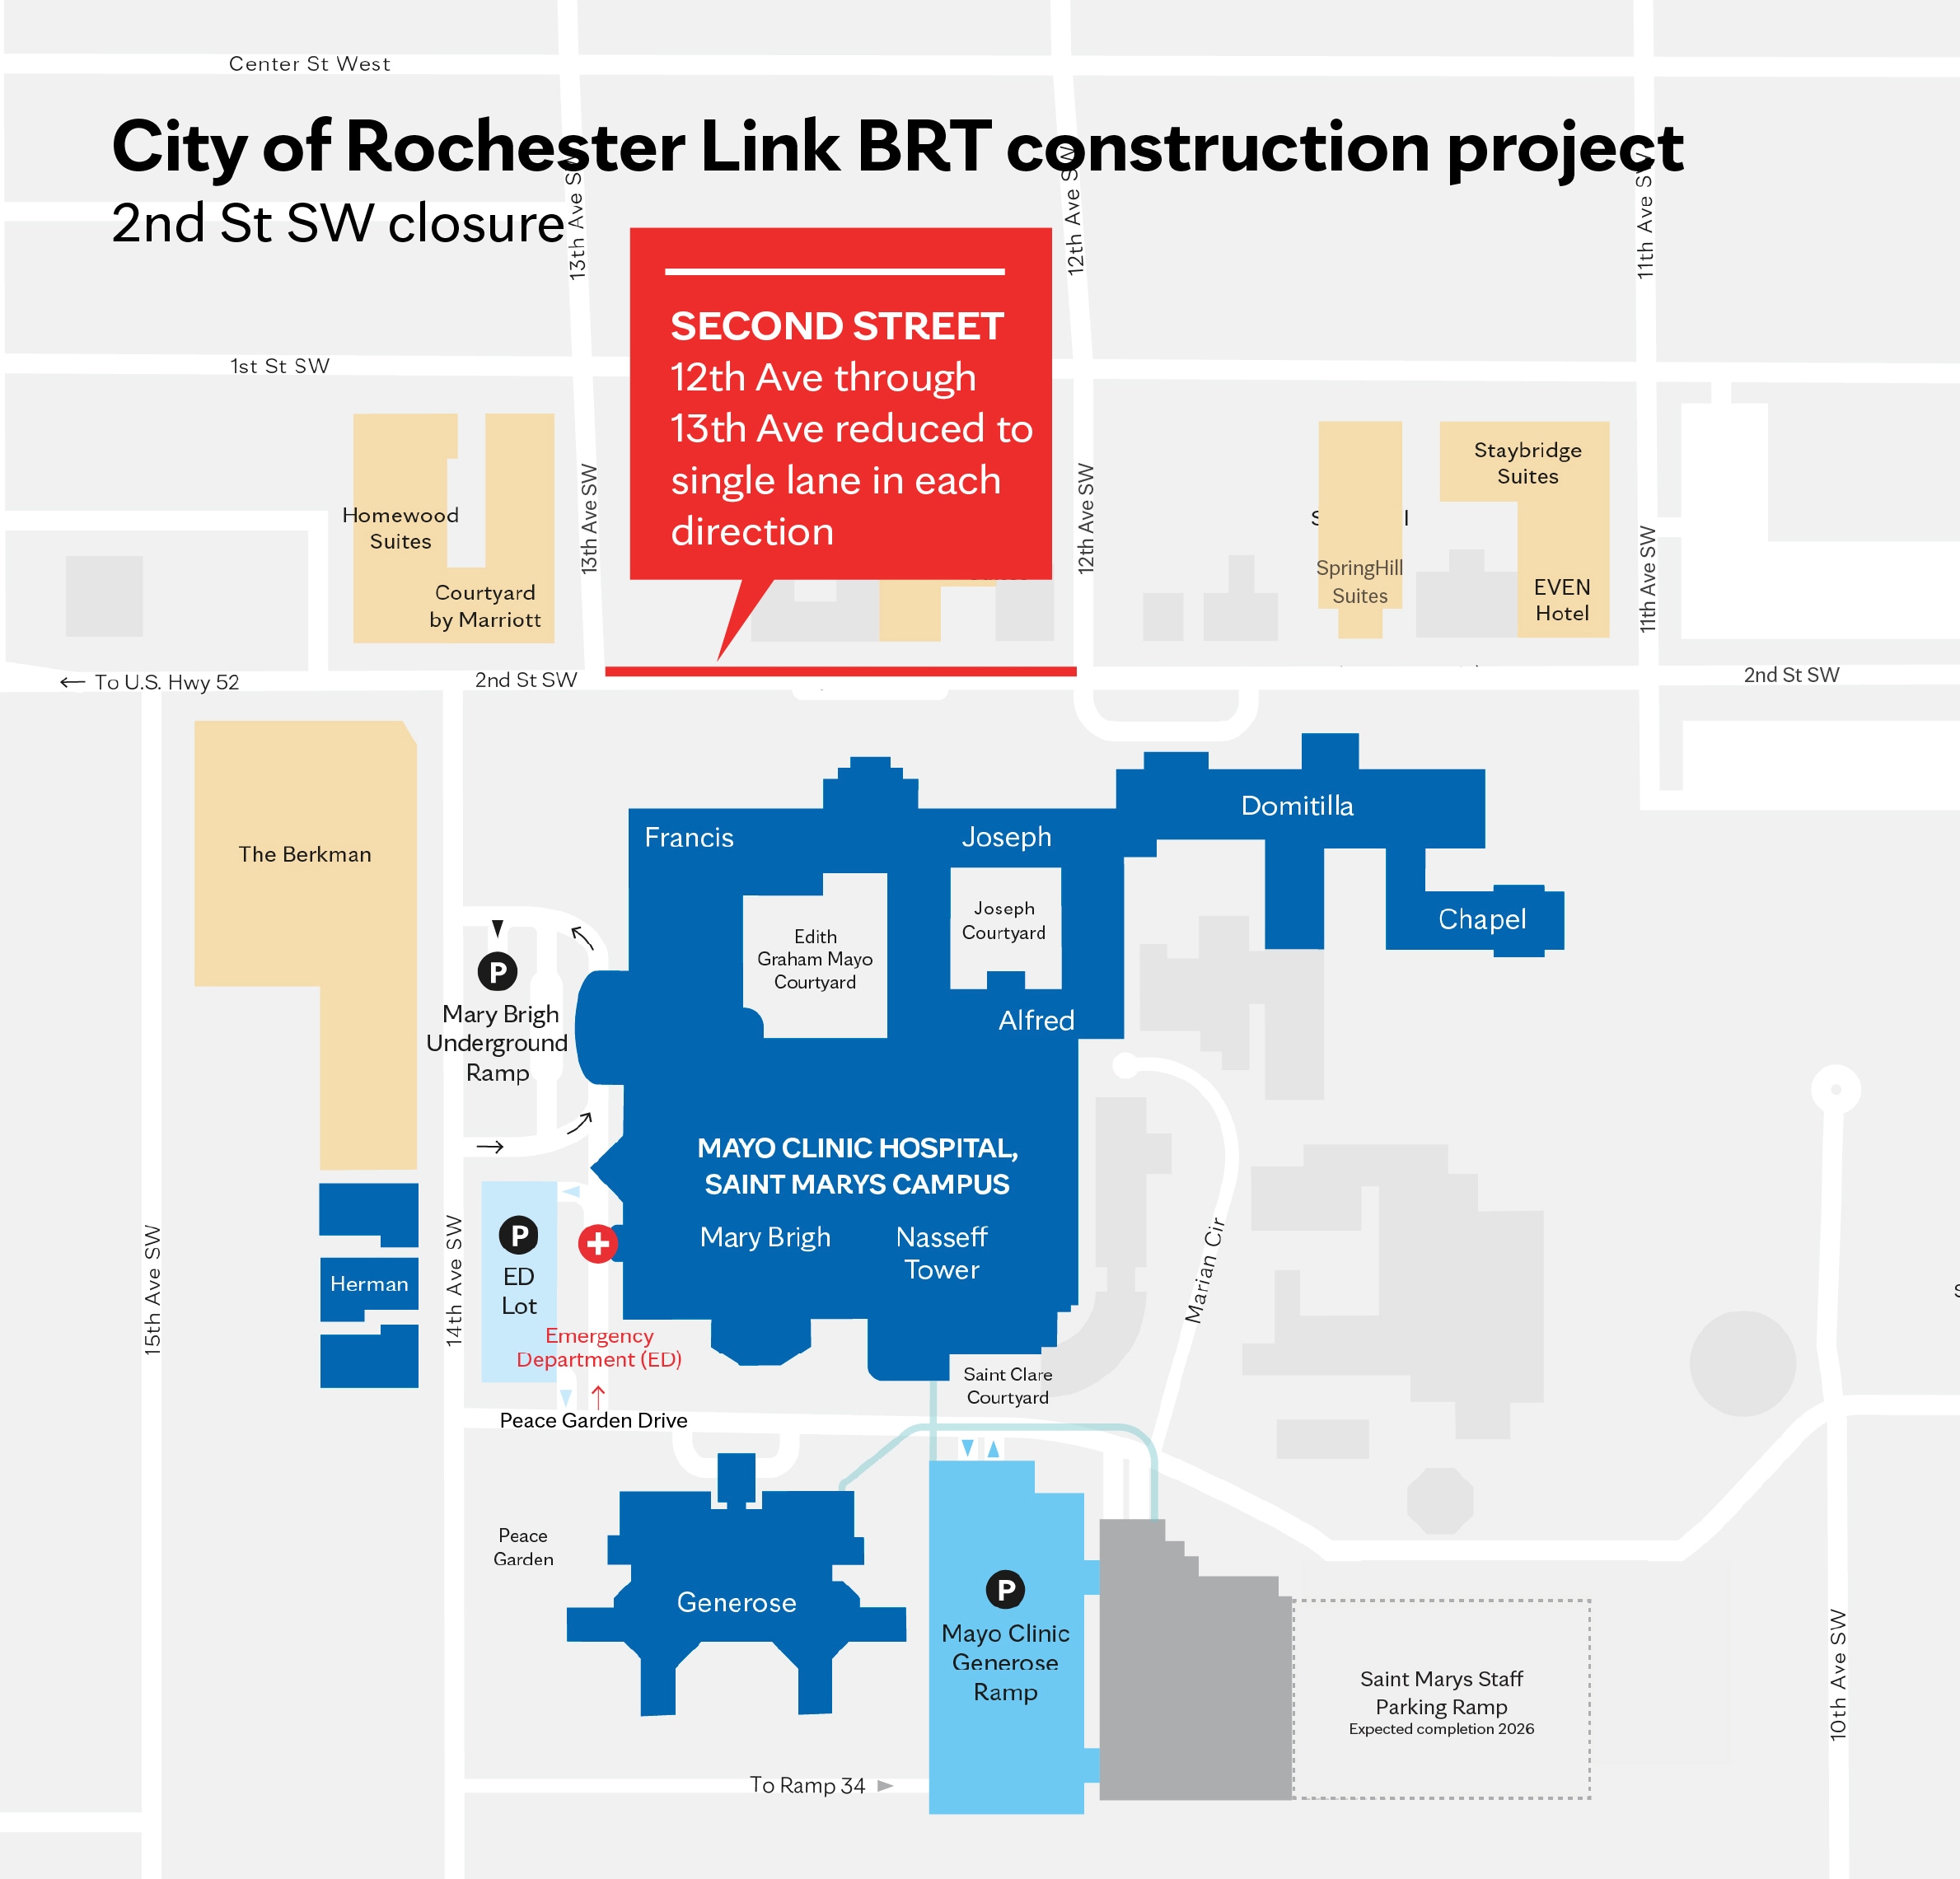
PUBLIC-SURFACE FINDING
Demand signals are strong. The missing layer is attribution: which channel, order source, event and menu family turns that demand into retained cash?
03 / Price-to-experience alignment
The product can command the price.
The experience must prove it.
A roughly $15 lunch deal and $20+ full combo create a premium expectation before the first bite. Every visible surface, menu decision and digital touchpoint either supports that price—or makes the customer question it.
THE CUSTOMER’S TEST$15–$20+
“Does the full experience feel worth what I am about to spend?”
OPERATING OBSERVATION
Great food is carrying avoidable presentation friction.
Cleanliness, menu coherence, navigation and photography influence trust, conversion, average ticket and repeat intent. The room and digital experience should make the food easier to buy—and the price easier to understand.
01
PHYSICAL STANDARD
Customer-ready must be consistent every shift.
Benches, seats, tabletops and ordering kiosks need a visible standard that supports the food and price point at every service.
AXLETE INSTALLSA 10-point front-of-house standard, opening/shift-change/closing checks, named ownership and weekly photo verification.
PROOFAudit pass rate · review language · repeat visits
02
MENU SYSTEM
Digital boards and a large chalkboard compete.
Customers must reconcile multiple menu surfaces. That adds decision friction, weakens price communication and makes deliberate upselling harder.
AXLETE INSTALLSOne menu hierarchy, one pricing source, daypart logic, clear modifiers and a controlled special-board role.
PROOFOrder time · mix · attachment · average ticket
03
DIGITAL FLOW
The website makes customers work.
The current structure feels dated and does not create a clean path from appetite to menu, order, catering inquiry, truck booking or visit.
AXLETE INSTALLSA mobile-first revenue map, rebuilt navigation, channel landing pages, source tracking and a measurable order/lead path.
PROOFClicks to order · qualified leads · conversion · source
04
APPETITE PROOF
The photography undersells the food.
The current imagery shows the product but does not consistently communicate heat, texture, portion and craveability at a premium-meal standard.
AXLETE INSTALLSA prioritized shot list, visual standards and a reusable content library mapped to web, ordering, social and catering sales.
PROOFContent CTR · item mix · order conversion · reuse
CUSTOMER PATH
CURRENTSearch visibility→Menu + ordering→Limited attribution→Unmeasured value
TARGETAppetite image→Clear value + menu→Order / book / visit→Tracked revenue
Search + marketing
Customers already find Jersey Jo’s.
Make the next step earn.
The next job is to turn existing attention into completed orders, catering deposits and repeat business.
OBSERVED GOOGLE SEARCH · OCT. 24, 2026
“philly cheesesteak Rochester MN”
1stOrganic website result
2ndLocal map pack
1.3KApprox. Google reviews
One dated search observation. The baseline is visibility; the business result is completed contribution.
View observed search example ↗AXLETE PRIORITYPreserve visibility.
Preserve visibility.
Improve the buying path.
Clear menu. Strong food photography. Direct ordering. Searchable catering packages. A truck-booking path with someone responsible for the reply.
Test the contribution case ↓SEARCH + ORDERING
Make a hungry customer’s next step obvious.
Keep the pages that already earn traffic. Simplify the menu, ordering choice, pickup instructions and mobile path; align Google hours and links with the operation.
AXLETE BUILDS
A search-to-order map, photography priorities and source tracking through completed orders.
PROOFOrder completion · net ticket · contribution by source
CONTENT THAT DOES A JOB
Show the food. Photograph the signature meal, portion and preparation. Give it a destination. Send each post or campaign to ordering, a catering package or an event date. Close the loop. Record the order, deposit and contribution.
04 / Seasonal cash architecture
Do not average a business
that lives in extremes.
The reported $2K–$40K monthly range describes a seasonal operating cycle. Adjust the planning inputs below to see how rent exposure and peak-season reserve requirements change.
EDITABLE PLANNING INPUTS
Build the annual sales shape
The starting scenario uses management’s reported monthly range. Adjust it to match the books.
ILLUSTRATIVE ANNUAL SALES$240K
BASE RENT / SALES35.0%
LOW-MONTH RENT GAP$5K
$7K monthly base rent
MANAGEMENT IMPLICATION
Peak months must do more than produce sales—they must build the reserve and booked pipeline that carry fixed obligations through winter.
MONTHLY SALES$2K350%rent burden
MONTHLY SALES$10K70%rent burden
MONTHLY SALES$20K35%rent burden
MONTHLY SALES$30K23%rent burden
MONTHLY SALES$40K17.5%rent burden
05 / Six-engine operating company
One brand.
Six accountable economics.
Each channel needs its own sales, direct costs, contribution, owner and cash forecast. Select an engine to see the management question and AXLETE output.
BASELINE PROFIT ENGINE
Can the restaurant produce dependable weekly contribution through every season?
Separate dine-in, pickup, first-party delivery and third-party delivery economics; then optimize menu contribution, labor deployment, purchasing and construction-period traffic.
AXLETE OUTPUTWeekly restaurant contribution scorecard and ranked operating actions.
Mobile lease-coverage model
Can booked events cover the entire base lease?
Move the inputs. The model tracks contribution after event-specific food, labor, travel and other variable costs—but before shared overhead, taxes and financing.
Events × average sales × contribution margin
MONTHLY EVENT CONTRIBUTION$7,200
103%of base rent
This scenario covers the $7,000 monthly base rent.
06 / Occupancy + property architecture
Choose the location
that strengthens the business.
Compare the current lease, a qualified relocation, an additional operation and eventual ownership. The decision must improve cash flow and work with management coverage.
IMPROVE THE EXISTING BASE
Make the present location carry its cost.
Negotiate from a clear cash forecast, improve access and ordering, and grow booked catering around the kitchen already in place.
REPORTED CURRENT BASE RENT$84,000 / yearBefore utilities and other occupancy costs.
THE DECISION TEST
Can better terms and operating contribution make staying the strongest option?
AXLETE OUTPUT
A lease negotiation case and a downside cash forecast, compared with the cost of moving.
WHAT MUST BE KNOWN
Full lease obligations, access plan, channel contribution and achievable negotiated terms.
LOCATION TO QUALIFYSoldiers Field: an option to evaluate.+
The City reviewed a 2027 concession process.
August 2026 records document a competitive process and review of proposals for the clubhouse. Current availability, financial terms and operating rights need confirmation before a recommendation.
49,867Open-swim visits in 2025. The aquatic center had a separate concession operator; these are not exclusive clubhouse customers.City pool report ↗
Access mattersThe City’s 6th Street Bridge program extends into spring 2028. Confirm current parking, loading and construction phases.City construction program ↗
Compare full occupancy cost, service rights and manager coverage. A low advertised rent alone does not decide the move.
If ownership is the right next step
Choose the structure with the numbers in view.
For Jersey Jo’s C corporation, compare operational simplicity, liability, tax and future-sale flexibility with the CPA, attorney and lender.
SIMPLER OWNERSHIP
Jersey Jo’s Inc. owns and operates from the building.
One borrower and one entity can simplify operations, but operating liabilities and real estate remain together and later property disposition may create additional tax friction.
POTENTIAL ADVANTAGESimpler entity and lender administration.
PRIMARY QUESTIONDoes simplicity outweigh liability and exit constraints?
MODEL WITH CPA · ATTORNEY · LENDER
FEDERAL C-CORP RATE21%Before credits and adjustments
MINNESOTA CORPORATE RATE9.8%Taxable bases differ; do not simply add
UNDERWRITING FILE1120 + M4Plus officer pay, retained earnings and shareholder activity
CAPITAL RULECash firstDebt capacity follows normalized contribution
07 / Capital stack
Assign the right dollars
to the right decision.
Loan ceilings are not borrowing capacity. Grants do not rescue weak economics. Every source must match an eligible cost, approval sequence and repayment case.
01Operating improvements
Menu, labor, purchasing, access, booking and attribution.
02Project incentives
Rebates or reimbursement only when the project already works.
03Equipment + working capital
Debt sized to proven repayment capacity.
04Property financing
After normalized cash flow, reserves and equity are credible.
PROMISE Loan
Up to $1.5M · ≤3%Potential real estate, redevelopment and equipment lane. Revenue, location, lender and underwriting requirements still apply.
Official report ↗SBA 7(a)
Up to $5MEligible real estate, equipment and working-capital uses, subject to lender underwriting and program rules.
SBA overview ↗SBA 504
Up to $5.5M SBA portionLong-term financing for qualifying owner-occupied property and major fixed assets—not ordinary working capital.
SBA 504 ↗SMIF
Up to $200KUp to 50% of project cost with local lending participation, collateral, cash flow and guarantees.
SMIF program ↗RPU financing
Up to $25K · 0%Pre-approved qualifying efficiency projects completed through a participating service provider.
RPU program ↗Make It Minnesota
Up to $4KFY27 marketing cost-share for qualifying Minnesota-manufactured packaged brands after a compliant sauce path exists.
MDA program ↗PROGRAM DISCIPLINE
The current MPCA organics program is a competitive statewide pool. It belongs in the plan only if Jersey Jo’s has a qualifying project whose economics work without grant funding.
Verify current programs ↗08 / Owner independence
A company Joe owns.
Not a job that owns Joe.
The long-term ambition is a $5M+ enterprise that pays its obligations, survives disruption, runs through leaders and gives Joe’s family the choice to own it. The near-term job is to build the cash flow and management depth to support that ambition.
THE DESTINATION$5M+
Owner-independent enterprise value.
The exact timing follows verified economics. The operating architecture starts now.
A forward cash view and reserve replace catch-up.
Leaders, standards and escalation rules run service.
Catering, mobile, delivery and repeat accounts absorb disruption.
Lease leverage and ownership come from proof, not pressure.
Channel economics, 13-week cash, rent plan, customer-experience reset and weekly scorecard.
GATE · Know where every dollar is made or lost.Contracted catering, mobile calendar, menu discipline, SOPs, reserve funding and manager bench.
GATE · Fixed obligations are covered before the month starts.General manager, channel owners, incentive scorecards and a weekly CEO operating review.
GATE · Joe can leave without revenue or standards falling.Add the next location, commissary or owned facility only after cash, leadership and debt tests clear.
GATE · Expansion does not depend on heroic owner hours.A portfolio of restaurant, catering, mobile, events and packaged products with professional management.
ROLE · Joe leads strategy, people, partnerships and capital.LANDLORD EXPOSURELease leverage → relocation option → ownership readiness
TRAFFIC EXPOSUREWalk-in dependence → booked and recurring demand
OWNER EXPOSUREJoe on every shift → leaders with authority and standards
FAMILY LEGACYOperating continuity → family ownership by choice
09 / 30-day 360° diagnostic
From visible friction
to quantified decisions.
AXLETE will reconcile the economics, reset the customer experience, repair the revenue paths and produce the operating and capital system Joe can use weekly.
RECONCILE + SEPARATE
Build the channel-level economic truth.
Reconcile POS, bank, merchant, payroll, tax and cash records across restaurant, delivery, food truck, trailer and catering.
RECONCILED P&Ls13-WEEK CASH FORECASTWINTER RESERVE TARGETCATERING PIPELINEEVENT CONTRIBUTIONPROPERTY DECISION MODELLENDER PACKAGE90-DAY EXECUTION PLAN
10 / AXLETE value creation
We install the system.
We measure the result.
AXLETE operates as the fractional growth, finance and implementation office: building the tools, coordinating execution and showing what changed in cash terms.
THE OPERATING AGREEMENT
Implementation over recommendations. Operating proof over vanity metrics. Cash flow before property.
Every workstream has a baseline, an owner, a deadline, a measurable output and a weekly decision attached to it.
VALUE LEVERAXLETE BUILDS + RUNSVALUE CAPTUREDWEEKLY PROOF
Channel P&Ls, menu contribution, labor and delivery economics.
Stop subsidizing weak channels with strong ones.Contribution by channel · labor hour · itemFront-of-house standard, menu architecture, photography brief and digital revenue map.
Defend the ticket price and reduce customer hesitation.Audit rate · ticket · mix · conversionCatering packages, account list, follow-up cadence, deposits and mobile calendar.
Convert seasonal assets into contracted contribution.Pipeline · close rate · deposits · event margin13-week cash forecast, reserve target, lease-versus-buy and OpCo/PropCo model.
Avoid borrowing ahead of proof and preserve options.Cash floor · DSCR · equity need · downside caseOne dashboard, named owners, response SLAs and a ranked weekly action list.
Turn data into decisions while the week still matters.Owner · due date · result · next actionDAY 7Economic baseline
Data reconciled; channel and cash gaps visible.
DAY 14Experience reset
Room, menu, imagery and web priorities in execution.
DAY 21Revenue engine live
Packages, pipeline, booking and attribution operating.
DAY 30Decision system
Weekly scorecard and 90-day plan owned and active.
The operating target
$4,500–$6,000 more
monthly contribution.
A target to validate and earn—not a sales forecast. Build it from completed orders, profitable events and verified expense reductions, before AXLETE fees and other execution costs.
10 additional orders a day × 26 days × $20 net ticket × 35% contribution.
AXLETE: ordering path, food imagery, repeat-customer workflow and source tracking.4 additional completed events × $2,500 net sales × 30% contribution.
AXLETE: packages, account outreach, quote follow-up, deposits and event-level margins.Monthly purchasing, waste or scheduling savings checked against the books.
AXLETE: cost baseline, weekly variance review and named corrective actions.WORKED MONTHLY SCENARIO$5,320
$15,200 additional sales → $4,820 contribution + $500 savings.
Use actual food, labor, travel and fulfillment costs; exclude sales shifted from existing channels.
Reconcile the baseline, validate margins and capacity, launch packages and track qualified inquiries, quotes and deposits.
Measure completed incremental business and realized savings, less execution costs. Test winter and peak months separately before expanding commitments.
Assign inquiry response, event preparation and shift standards to named owners. Track Joe’s weekly operating hours and service quality—not just sales.
Editable contribution model
What contribution
can the work create?
Adjust four distinct value levers for one month. Then add your execution costs to see the operating result and payback.
01 · Additional orders
Count completed orders gained through better conversion or repeat demand. Exclude orders only moved between channels.
02 · Additional catering
Use the contribution after food, event labor, travel, fees and supplies. Count events additional to the current calendar.
03 · Direct-order margin
Use the fee difference after direct payment, delivery and fulfillment costs. These orders are separate from additional orders above.
04 · Operating efficiency
Use reductions that can be checked against the books. Exclude fee savings counted above and any unconfirmed location savings.
Your execution costsOPTIONAL
Include approved engagement, media, technology, incremental staffing and other execution costs. Use the full budget for the work you want to model.
MONTHLY CONTRIBUTION BEFORE EXECUTION COSTS$2,170
Additional orders$910
Additional catering$900
Direct-order margin$160
Operating efficiency$200
AFTER MONTHLY EXECUTION COSTSAdd your budget
ONE-TIME INVESTMENT PAYBACKAdd costs + investment
Planning example. Replace the inputs with your operating figures; test a winter month and a peak month separately.
Before shared overhead not included in the inputs, taxes, debt service and changes in working capital. Payback assumes the entered monthly result continues.PUT THE IMPROVEMENT TO WORK
Keep obligations current → build the reserve → fund management coverage → invest in proven growth.
C corporation · after-tax economics
Grow the contribution.
Deduct eligible costs.
Reinvest the cash.
Ordinary and necessary operating services can reduce corporate taxable income while improving the business. At a 21% federal corporate rate, each $1,000 of fully usable current deductions reduces federal tax by $210—an after-tax cost of $790.
One engagement. Coordinated business value.
AXLETE connects menu and labor economics, marketing and ordering, booked catering, cash management, capital readiness and implementation. Evaluate the work on contribution created, after-tax investment and cash retained—not a list of disconnected advisory services.
Legitimate operating services generally qualify as business expenses. The deduction lowers taxable income while the business receives the work. As profit grows, coordinate deductions, estimated taxes and reinvestment with the CPA.
In the worked case: $63,840 annualized contribution less $24,000 of modeled operating-services spending leaves $39,840 before federal tax. The eligible spending reduces federal tax by $5,040 compared with the same contribution without that deduction. After the remaining incremental federal tax, $31,474 is retained.
That $5,040 benefit is already included in the retained result—not another gain to add. The $2,000 monthly budget is a modeling assumption, not an AXLETE quote; contracted scope and external costs must be agreed separately.
EDITABLE WORKED CASE · ANNUALIZED · FEDERAL ONLY
Assumptions: $5,320 monthly contribution, $2,000 monthly spending fully currently deductible, and $0 baseline taxable income. These are not Jersey Jo’s established results.
YOUR ANNUALIZED VALUE BRIDGE
Contribution created before execution costs$63,840
Less consulting + execution spending−$24,000
Additional operating cash before tax$39,840
Less incremental federal tax at 21%−$8,366
Additional cash after spending + federal tax$31,474$2,623 monthly equivalent
Annual federal tax reduction from eligible spending, compared with the same contribution before that deduction.
Total annual spending less its modeled federal tax benefit.
Current obligations → winter reserve → management coverage → proven expansion. Lower owner dependence is measured separately in operating hours, not assigned an invented dollar value.
One model. No double-counting. CPA-ready records.
The bridge assumes each entered month repeats for 12 months; it is a run-rate comparison, not a seasonal forecast. Contribution must be after direct operating costs and verified savings must be real. The model subtracts the full execution budget and allows only the eligible portion as a current deduction, capped at that budget. Excludes Minnesota taxes, credits, loss carryforwards, one-time setup, other overhead, debt service and working-capital needs. Federal tax is compared before and after the improvements; no immediate loss refund is assumed. Current deductibility and timing depend on the services and tax position. Acquisition, financing, development and improvement work may need different treatment. Actual spend, classification and tax payments are reconciled with the CPA.
JOE OWNS
Fast decisions. Data access. Operating authority.
AXLETE cannot manage around missing records or delayed calls. Joe keeps the work grounded and clears the decisions that only the owner can make.
AXLETE OWNS
Build. Implement. Measure. Hold the line.
We create the models and systems, coordinate specialists and vendors, run the cadence and tie every action back to contribution, cash or capital readiness.
The decision sequence
Profitability earns optionality.
First make the current business cleaner, easier to buy from and economically visible. Then turn catering and mobile assets into booked contribution. Property comes after the proof—not before it.
01StabilizeRestaurant cash contribution
→
02MonetizeCatering + mobile assets
→
03ValidateLiquor + sauces
→
04CapitalizeProperty ownership
THE SESSION MUST ANSWERWhere does cash leak today?Which fixes start next week?What must be true before buying property?
Scope and fee will be finalized after financial access and the diagnostic workplan are confirmed.